

Tell us about the project
Start a business insurance request. A broker may follow up for plans, values and site details; submitting does not bind coverage.
Request a construction quote →Terms and eligibility are subject to insurer review.Course of construction • British Columbia
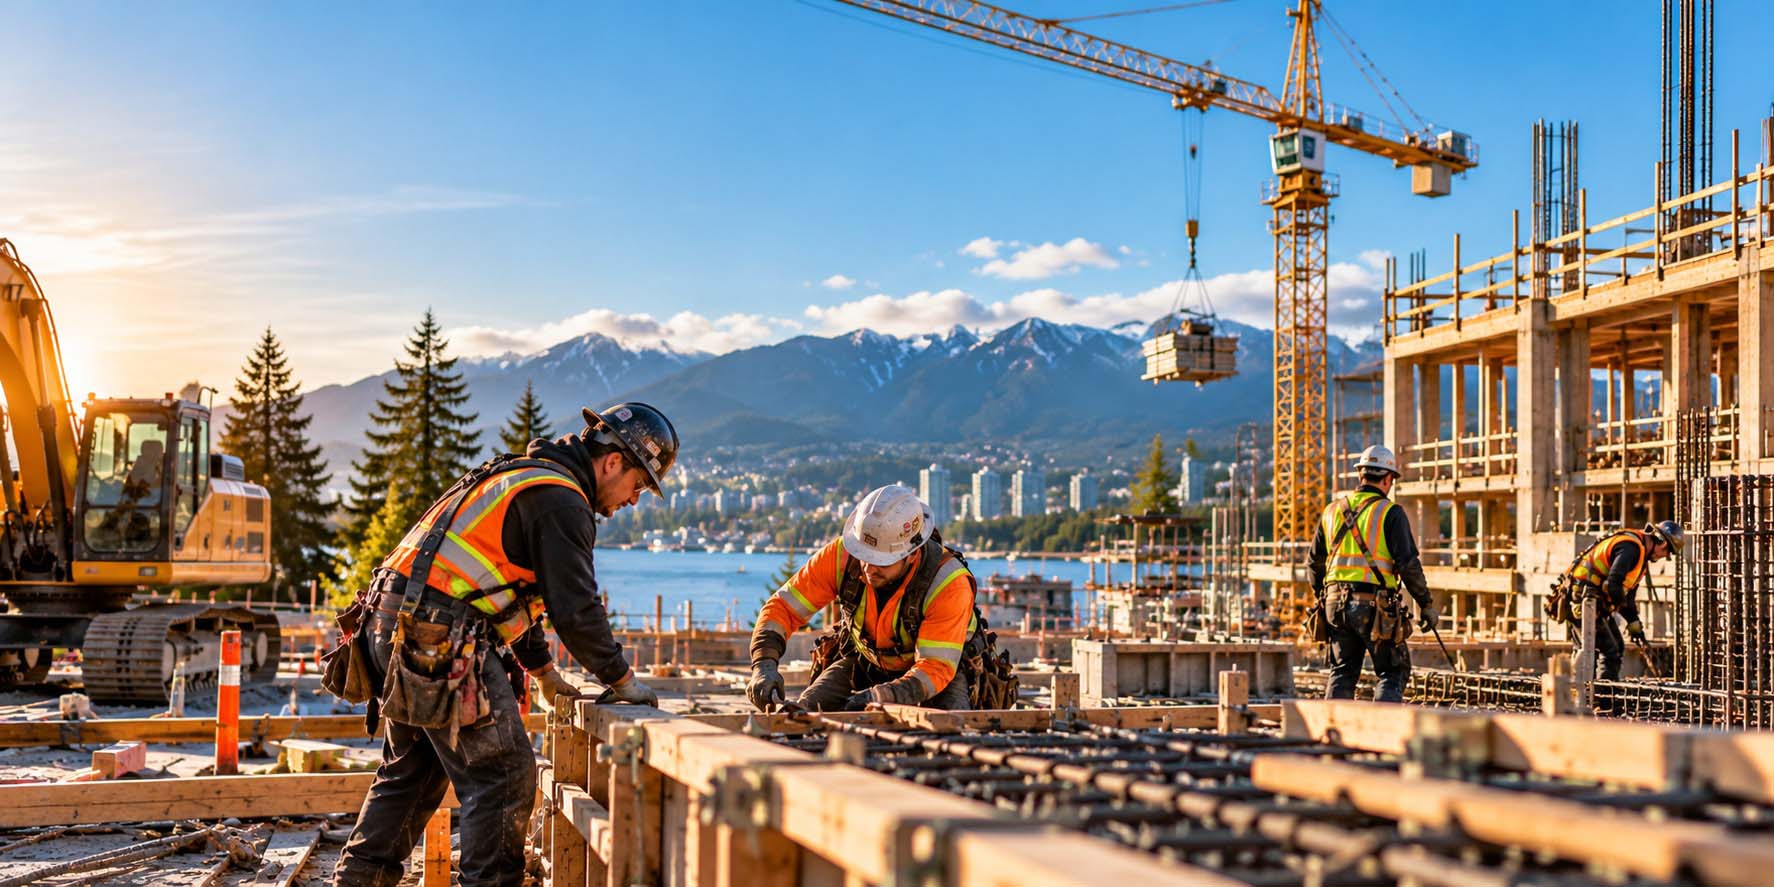
A fire damages framing before handover. Materials disappear from a secured site. Course of construction (COC), also called builder’s risk insurance, may help protect an insured building project against covered physical loss or damage during construction.
The online form starts a quote request. A broker may contact you to review your operations; coverage is not activated by submitting it.
Prefer to talk? 1-833-660-9926
Plan your project protection
Tell Western Coast about the build, its estimated completed value and schedule. As your broker, we can discuss available insurer options and explain project-specific conditions.
Start a business insurance request. A broker may follow up for plans, values and site details; submitting does not bind coverage.
Request a construction quote →Terms and eligibility are subject to insurer review.Discuss building type, trades, security, site location, start and completion dates.
Call 1-833-660-9926Explore Western Coast locations and call ahead to confirm construction insurance support.
Find a branchWho needs it
Course of construction insurance is designed around a specific project, rather than every risk faced by a contracting business.
A new house under construction may be exposed to fire, vandalism and theft before completion.
Projects involving multiple trades require clear decisions about insured parties, values and responsibility.
Owners financing a new build may need evidence of construction property coverage under lender terms.
Major alterations can expose new work and existing structures to different risks; confirm how each is insured.
Retail, office and mixed-use projects may need project-specific limits, extensions and occupancy conditions.
Subcontractors should confirm whether they are included on the project policy and insure their own tools separately.
Protection during the build
Builder’s risk policies may cover direct physical loss or damage to insured construction works from specified or otherwise covered perils. The insured property, period and extensions depend on the wording.
Scroll horizontally on smaller screens to compare details.
| Protection | Example | What to check |
|---|---|---|
| Building under construction | Fire damages partially completed framing. | Confirm insured works, valuation basis and applicable deductibles. |
| Materials at the site | A covered theft removes installed or stored construction materials. | Review theft conditions, security warranties and sublimits. |
| Materials in transit or storage | Materials are damaged before delivery or while stored away from site. | Off-site storage and transit may need specific extensions. |
| Temporary works | Scaffolding or temporary structures are damaged by an insured peril. | Confirm which temporary works are included or excluded. |
| Weather-related loss | A windstorm damages insured work in progress. | Review flood, earthquake, water and wind restrictions. |
| Delay-related soft costs | A covered property loss delays completion and creates eligible additional costs. | Soft costs and delay-in-start-up require specific terms and waiting periods. |
Examples are illustrative. Theft, transit, flood, earthquake, existing property and soft-cost coverage may be excluded, limited or available by endorsement. Review policy wording.
Discuss construction coverage →Important distinctions
A builder’s risk policy protects eligible project property; it is not a substitute for a contractor’s full insurance programme.
The cost of correcting defective design, materials or workmanship may be excluded. Resulting damage can be treated differently under some wordings.
Injuries to third parties, vehicle accidents and employee workplace injuries generally require separate liability, auto or WorkSafeBC arrangements.
Contractors’ tools, mobile equipment, existing buildings, flood, earthquake and pollution may be excluded or need separate coverage.
Project cost & value
Insurers assess the project itself and the protection requested. Costs vary with the risk, schedule and insurer underwriting.
Why Western Coast
Western Coast is your insurance broker. We help BC project owners and contractors compare available course of construction options, identify gaps and understand coverage from groundbreaking through handover.
Review covered works, deductibles, named insureds and optional extensions.
Discuss construction methods, weather exposures, site security and lender terms.
Ask about changes in project value, timing, scope or occupancy before they affect your cover.
“I was very well served here by Thomas, issuing the registration and insurance for my company's commercial vehicle.”
Jacob W. · Vancouver, BC · See branch information ↗“Kevin Ferris was very helpful in understanding my insurance requirements.”
Karen B. · Coquitlam, BC · See branch information ↗Customer feedback can help you assess local service, communication and support.
Western Coast branch directory · See branch information ↗Check the source and date of current reviews before making a decision.
Western Coast branch directory · See branch information ↗Local advice, close to home
Discuss construction insurance with a Western Coast broker. Call ahead to confirm the branch can help with your project.
View all branch hours & contact detailsLooking for another location? Open the full branch locator or call 1-833-660-9926.
Frequently asked questions
Course of construction (COC), also called builder’s risk insurance, may cover insured buildings and materials against certain physical loss or damage while a project is underway, subject to policy terms.
The owner, developer or general contractor may arrange a project policy, depending on the contract and financing. Confirm who is insured and whether subcontractors are included.
Not automatically. Contractors’ tools and mobile equipment often require separate coverage. Check any specific inclusions, sublimits and exclusions.
The cost of correcting defective work is often excluded. Some policies may cover resulting damage, subject to precise wording and exclusions.
Flood and earthquake may be excluded or available as optional coverage. Site location, insurer availability and deductibles affect the options.
Coverage can end at completion, occupancy, acceptance or another policy-defined trigger. Confirm the dates and handover arrangements with your broker.
Course of construction primarily addresses insured project property. Third-party injury and property damage liability generally need separate CGL or project wrap-up liability coverage.
Completed project value, building methods, location, fire protection, project duration, claims history, limits, deductibles and extensions can affect premiums.
The form starts a quote request. A broker may contact you for project details; an insurer must agree to terms and an effective date before coverage starts.
Keep exploring
Your next step
Tell us about your site, schedule and completed project value. Western Coast can help compare available course of construction policies.
Submitting a request does not activate insurance.
Coverage is subject to insurer eligibility, underwriting, policy terms, limits, conditions and exclusions. The policy wording governs.


Western Coast Insurance Services is a wholly owned division of Western Financial Group Ltd. Insurance products are underwritten by certain licensed insurance companies and are only available throughout British Columbia, Canada.